When Money Is More Than Money: Trauma, Spending, and Financial Healing
Some conversations stay with you long after the walk is over.
During our recent time living in New Zealand, my family joined a friend and her family for a sunny Sunday walk along Sumner Beach. As we walked, she asked about my work in financial therapy: how money and emotions intersect, why spending can become difficult to manage, and what healing can look like.
That conversation prompted me to join her for an episode of her podcast, Reviving Hope.
It also raised a question I wish we asked more often: What happens to someone when money becomes a source of distress?
We tend to notice the purchase, the unopened statement, or the argument. Understanding what happens before those moments can give us a more useful place to begin.
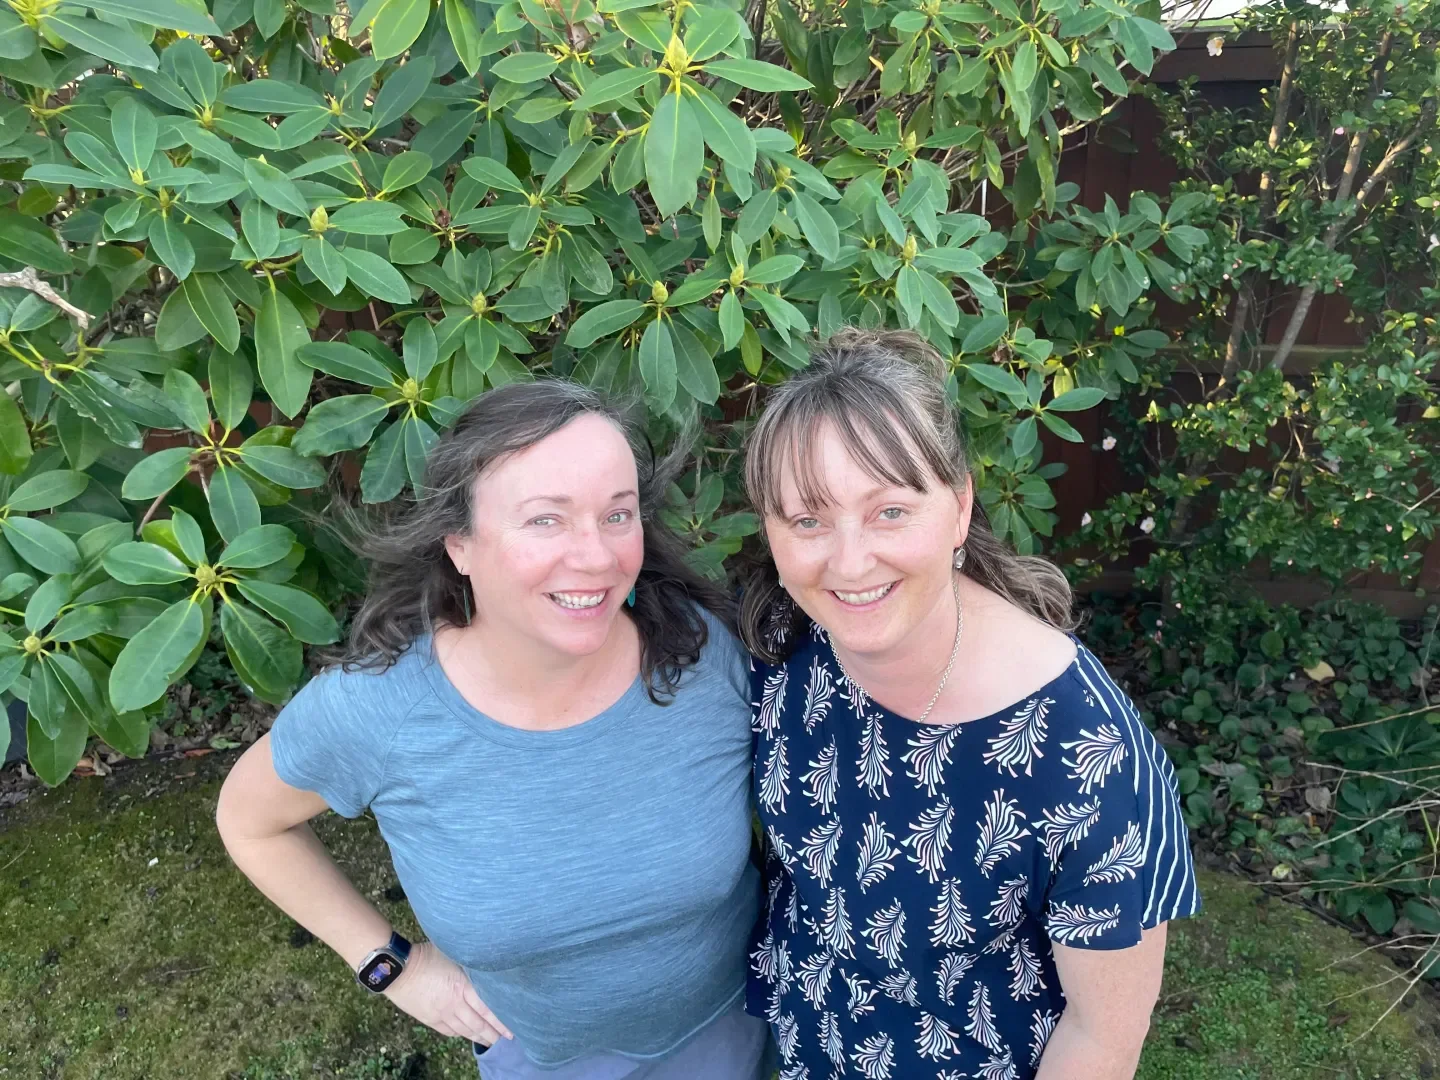
My friend, Bron, and I completed her Reviving Hope podcast in New Zealand, where we explored the intersection of money, emotion, and mental health. So grateful for a friendship that transcends continents and decades.
Financial therapy looks beneath the numbers
A budget can tell us where money goes. It may not tell us why opening a banking app feels unbearable, why spending brings relief, or why a conversation about expenses becomes a conversation about trust.
Financial therapy explores those connections. In my psychotherapy practice, I help people understand how their experiences, beliefs, emotions, and relationships shape their financial lives. Practical financial habits belong in that work, alongside attention to the emotional barriers that can make those habits difficult to sustain.
Someone can understand the numbers and still feel afraid. They can earn a comfortable income and struggle to spend on themselves. They can want to save and repeatedly turn to shopping after a difficult day.
Those patterns deserve curiosity. What does money represent: safety, freedom, belonging, independence, or the possibility of being cared for?
What is spending doing for you?
Buying something can offer pleasure, convenience, or a needed resource. Sometimes it also offers temporary relief from loneliness, overwhelm, grief, or uncertainty.
Imagine finishing a day in which everyone needed something from you. Scrolling through an online shop might offer a moment of possibility: something enjoyable, something you can choose, something just for you. The relief can be real, even when the purchase later creates more stress.
In therapy, I might ask:
What was happening just before the urge to spend?
What did you notice in your body?
What were you hoping the purchase would help you feel?
How did you feel afterward?
These questions help us understand the function of the behavior. Understanding it creates opportunities to respond to the underlying need while also addressing the financial consequences.
Trauma can be part of the story
For some people, money is connected to experiences of deprivation, instability, loss, or control. Exploring those experiences may help make sense of current patterns: spending quickly while money is available, holding tightly to every dollar, or avoiding financial conversations altogether.
These are possibilities to explore with a person, rather than conclusions to draw from their bank statement. Overspending does not automatically indicate trauma, and people who have experienced trauma respond in many different ways.
Our financial lives also happen within real conditions. Housing costs, disability, caregiving, discrimination, and unpredictable income affect what people can afford and how much stress they carry. Emotional support and practical resources often need to work together.
Creating a little room to choose
When an urge feels urgent, a small pause can help us notice what is happening. Grounding practices bring attention to the body and the world around us. The World Health Organization includes grounding, unhooking from difficult thoughts, and acting on values in its evidence-informed stress-management resources.[1]
Here is one way to practice a brief anchor:
Acknowledge what is here. Try: “I notice anxiety,” or “I’m having an urge to buy something.”
Connect with your body. Feel your feet against the floor or your back against the chair. Gently press your hands together or stretch.
Engage with your surroundings. Notice a few things you can see and hear. Bring your attention back to what you are doing.
Then ask: “What is one next step that supports what matters to me?”
That step might be making a planned purchase, closing the shopping app, checking your available money, or reaching out to someone. You can still feel uncomfortable while taking a useful step.
You might also experiment with a few gentle, comfortable breaths. Avoid forcing deep breaths or holding your breath. If focusing on breathing makes you feel more distressed or dizzy, return to noticing the room or the support beneath your feet.
Practicing in ordinary moments can make these skills easier to access during difficult ones. The aim is to develop more ways to respond, rather than expect yourself to feel calm all the time.
Compassion and practical changes belong together
Once you understand a spending pattern, you can design support around it.
For example, if online shopping tends to follow lonely evenings, a purchase delay may help, but so might making a plan for connection. If exhaustion is the trigger, rest and simpler routines may belong in the plan. Removing saved payment details or unsubscribing from sales emails can add a useful pause at the moment of purchase.
Compassion leaves room for accountability. You can acknowledge that a behavior brought relief and also recognize that it is creating debt, secrecy, or conflict. From there, the work becomes more specific: what needs attention, what support is available, and what can change next?
Spending during mania needs a different level of support
Spending associated with bipolar mania or hypomania requires clinical attention. Mood episodes can involve changes in sleep, energy, activity, and judgment; bipolar disorder generally requires ongoing treatment, often including medication and psychotherapy.[2] Grounding and purchase delays can support a broader plan, but they cannot substitute for treatment of a mood episode.
During a period of stability, someone can work with their treatment team and a trusted support person to consider a financial safety plan. Options might include purchase alerts, agreed check-ins, or temporary spending limits. Any arrangement should be consensual, clearly defined, and reviewed, with attention to autonomy, privacy, and access to essentials.
If spending escalates alongside markedly reduced need for sleep, racing thoughts, or unusually elevated or irritable mood, contact the treating clinician promptly. Severe symptoms or immediate danger require urgent care.
Support after an episode matters too: help with the financial aftermath, relationship repair where needed, and a plan for recognizing changes earlier.
Moving toward financial flexibility
Financial healing can begin with a different question. Instead of asking only, “How do I stop doing this?” we can ask, “What is happening here, and what would help?”
In my work, that means making space for the money story, exploring beliefs, addressing emotional wounds where relevant, and connecting values with achievable actions. The process is tailored to the person and their circumstances.
You might begin by looking at one avoided statement, naming an urge before acting on it, or having a short, supported conversation with your partner. Small actions can help rebuild trust in your ability to engage with money.
The conversation that began on Sumner Beach reminded me how much becomes possible when we approach financial struggles with openness. We can take their consequences seriously while treating the person experiencing them with care.
Listen to the conversation: Find my Money and Emotion conversation on Reviving Hope.
Explore support: At Koru Financial Therapy, I provide psychotherapy for individuals and couples located in California, including support for financial anxiety, money shame, trauma-related concerns, and relationship conflict around money.
This article provides general education and does not replace individualized mental health care.
Resources
World Health Organization. Doing What Matters in Times of Stress.
National Institute of Mental Health. Bipolar Disorder.
About the Author
Mariah Hudler is a Licensed Clinical Social Worker, Certified Financial Therapist, and founder of Koru Financial Therapy, where she helps individuals and couples navigate the emotional side of money. She met her friend Bron, host of Reviving Hope, on her first day of work in New Zealand nearly 20 years ago. Bron’s kindness and inclusive spirit have been a cherished part of their friendship ever since. With both their lives touched by money, emotion, and mental health in different ways, this conversation offered a meaningful space to reconnect and explore those intersections together.
